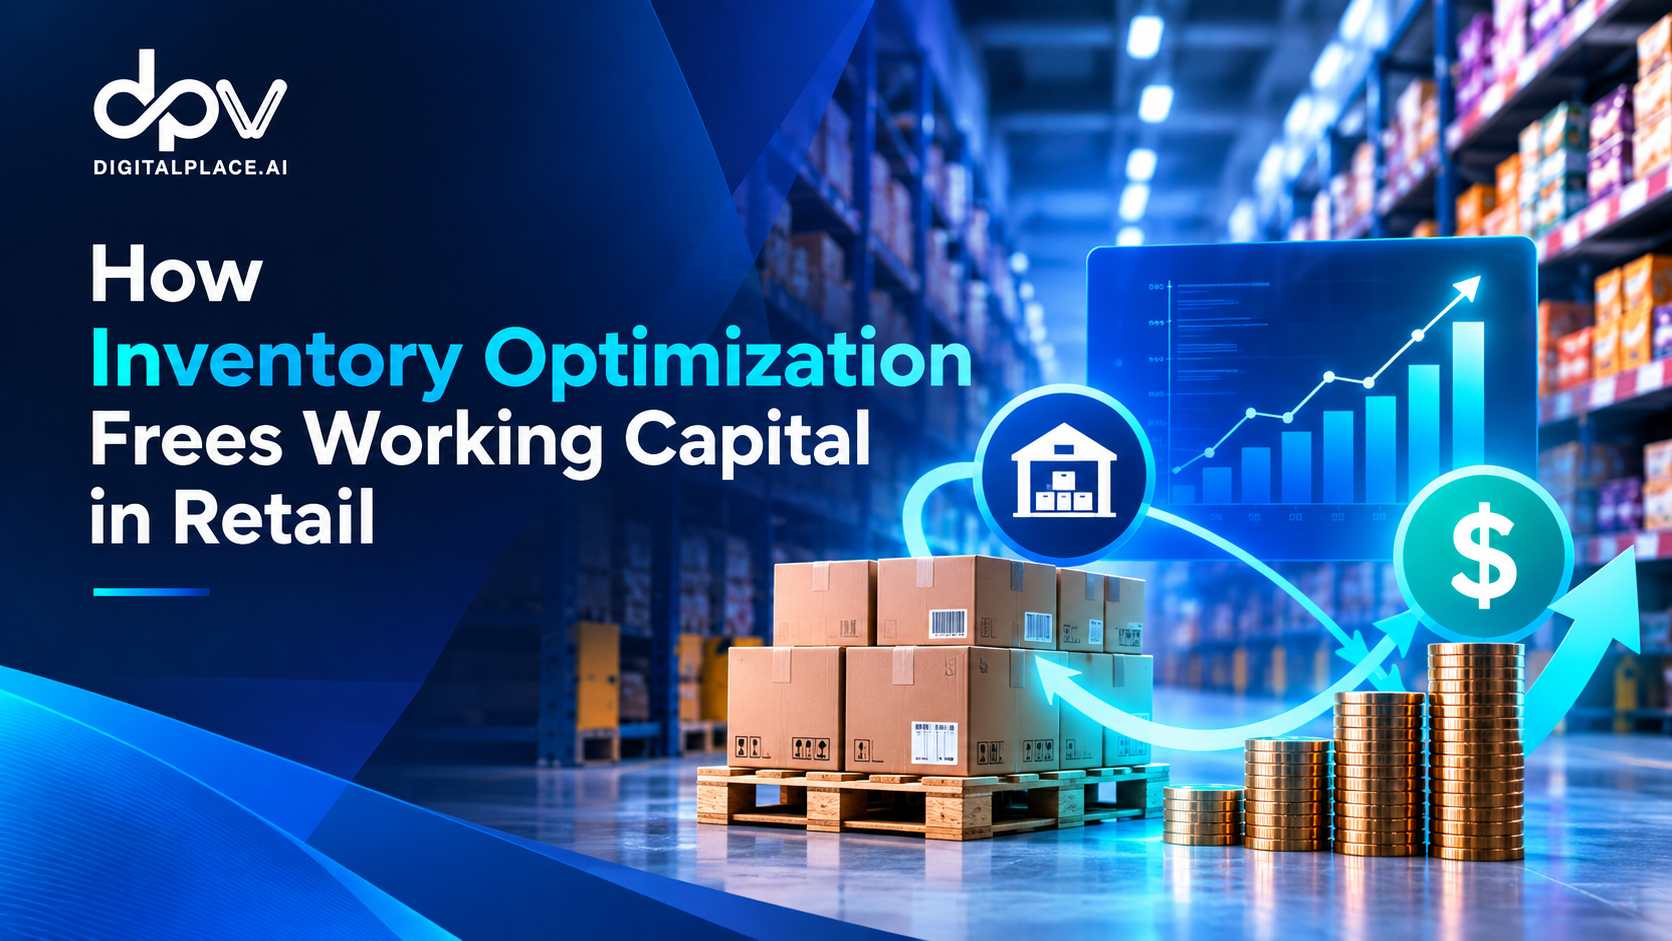
Inventory often looks like an operational asset: cartons in a distribution centre, cases in transit, products in a stockroom, and units sitting on shelves waiting to be sold. Financially, however, inventory is also cash that has already left the business but has not yet returned through a customer transaction. The longer that inventory remains unsold, the longer capital stays tied up.
Read more :
Demand forecasting in retail : Demand Signal Behind Every Sale
Demand Forecasting vs Inventory Optimization in Retail: What’s the Difference?
That makes inventory planning a working-capital issue as much as a supply-chain issue.
A retailer can appear well stocked and still have an inefficient inventory position. Too much capital may be sitting in slow-moving products, in the wrong stores, or at the wrong level of the network, while fast-moving items elsewhere remain unavailable. The challenge is therefore not simply reducing stock. It is determining which inventory is genuinely needed, where it should sit, and when it should be replenished.
That is where inventory optimization starts to have a direct financial impact.
The Inventory Problem Is Often a Cash Problem
Every unit of inventory represents a financial commitment. The retailer has purchased it, transported it, handled it, stored it, and allocated physical space to it before the item produces revenue.
When that inventory sells quickly, the capital cycle continues. When it sits for too long, the economics begin to change. Cash remains locked in stock while additional costs accumulate around it.
Those costs can include:
- warehouse and store storage;
- handling and internal logistics;
- shrinkage and damage;
- insurance and financing costs;
- markdown exposure;
- spoilage for short-life products;
- obsolescence as products or packaging change.
The problem becomes particularly visible when excess inventory exists alongside stockouts. The business has already committed cash to inventory, but that capital is not necessarily sitting where customer demand is occurring.
In that situation, the retailer can be overstocked and understocked at the same time.
Why Excess Inventory Quietly Consumes Working Capital
Excess inventory is often discussed as a storage problem, but storage is only one part of the cost. A more important question is what else the retailer could have done with the capital tied up in those products.
Suppose a retail network holds an additional $500,000 of inventory that is not required to support its desired service level. That money could potentially have funded store expansion, marketing, technology investments, debt reduction, supplier payments, or simply provided additional liquidity.
This is the opportunity cost of inventory.
The effect can be difficult to see because the cash has not disappeared; it has simply changed form. It is sitting in cartons, shelves, and warehouse locations instead of remaining available to the business.
Inventory optimization therefore has a financial objective alongside its operational one: reduce unnecessary inventory without reducing the retailer’s ability to serve demand.
DSI: The Link Between Inventory and Cash
One useful way to observe this relationship is through Days Sales of Inventory (DSI), which broadly indicates how long inventory remains in the business before being sold.
A rising DSI can signal that inventory is moving more slowly and that capital is remaining tied up for longer. A lower DSI can indicate that the business is converting stock into sales more efficiently.
But DSI should never be interpreted in isolation.
A retailer could reduce DSI aggressively by cutting inventory everywhere. If product availability falls and stockouts increase, that lower DSI may simply be hiding lost sales.
The objective is not:
Digitalplace.ai supports retailers as a demand forecasting and inventory optimization partner by linking demand predictions with replenishment and allocation decisions, helping teams evaluate inventory performance through measures such as DSI, out-of-stock rates, availability, and working-capital impact.
The objective is not:
“Get DSI as low as possible.”
It is:
“Reduce unnecessary inventory while protecting the level of availability the business wants to deliver.”
Digitalplace.ai supports retailers as a demand forecasting and inventory optimization partner by linking demand predictions with replenishment and allocation decisions, helping teams evaluate inventory performance through measures such as DSI, out-of-stock rates, availability, and working-capital impact.
Cutting Inventory Is Not the Same as Optimizing Inventory
This distinction is fundamental.
An inventory-reduction programme often begins with a financial target: reduce stock by 10%, 15%, or 20%. Inventory optimization starts somewhere else. It asks how much inventory is needed to support expected demand under real operational conditions.
Those conditions include lead time, demand variability, service-level expectations, minimum-order quantities, display requirements, goods already in transit, and the amount of stock available elsewhere in the network.
The result may still be lower inventory, but the reduction is a consequence of better decisions rather than an arbitrary target.
A useful principle is:
The goal is not minimum inventory. It is the minimum inventory required to support the desired level of availability.
That sounds like a small distinction, but financially it is important. Cutting inventory without understanding demand can release cash temporarily while creating future stockouts. Optimization tries to release capital from stock the retailer does not need while preserving stock that protects revenue.
The Real Cost Comes From Inventory Misalignment
Total inventory can be misleading.
Imagine a retailer with three stores carrying the same product. Store A has three months of stock, Store B has roughly the right amount, and Store C is expected to run out within two days.
From a company-wide perspective, there may be plenty of inventory.
From a customer perspective, the product is unavailable in Store C.
This is not purely an inventory-volume problem. It is an inventory-location problem.
Capital can therefore be trapped in several ways:
- the wrong SKU;
- the wrong store;
- the wrong distribution centre;
- too early in the supply cycle;
- too much safety stock;
- inventory that no longer reflects current demand.
A business can have significant working capital invested in inventory while real demand still goes unserved.
How Much Capital Could Be Tied Up in Excess Inventory?
This simple scenario helps explain the relationship between inventory value and capital tied up in stock. It is an educational illustration, not a forecast of actual financial results.
Adjust the hypothetical inventory value and assumed excess-stock reduction. The module estimates how much less capital would remain tied up in inventory if inventory value fell by that amount.
This represents a simplified reduction in inventory value, not an automatic or immediate cash-flow increase.
Example: $1,000,000 × 15% = $150,000 less capital tied up in inventory. This does not mean the business automatically receives $150,000 in cash at once. Actual cash-flow effects depend on purchasing cycles, supplier payment terms, receivables, and the timing of inventory conversion.
Inventory Reduction Alone
Cutting stock without understanding demand may reduce inventory value, but it can also increase stockouts and lost sales.
Inventory Optimization
The objective is to reduce unnecessary inventory while maintaining the service level and availability the business requires.
Inventory is one component of operating working capital, but working capital also depends on items such as accounts receivable and accounts payable. A reduction in inventory value may reduce capital tied up in stock, but the actual cash impact will vary according to how inventory is purchased, sold, paid for, and converted into cash.
 Educational illustration only. Figures are hypothetical and should not be
interpreted as guaranteed operational, accounting, or financial outcomes.
How Demand Forecasting Influences Working Capital
Working capital is affected long before inventory reaches the shelf. It begins with assumptions about future demand.
If demand is consistently overestimated, replenishment quantities tend to be too high. The result may be excess inventory, higher DSI, greater markdown exposure, and more capital tied up than necessary.
If demand is underestimated, the retailer faces a different problem: inventory is lower, but so is the ability to capture sales.
Better demand forecasting helps narrow that gap, especially when models can distinguish between normal demand and temporary effects such as promotions, seasonality, bulk purchases, or unusual volatility.
But forecasting alone does not release working capital.
The financial impact appears when those forecasts influence what the retailer actually orders and where that inventory is placed.
Replenishment Is Where Forecasting Becomes a Financial Decision
A forecast may predict that a store will sell 120 units next week. The working-capital consequence depends on what happens next.
If the store already has 90 units available and another 20 are in transit, ordering another 120 units would create a very different financial outcome from ordering only the quantity needed to cover the remaining requirement and inventory rules.
The replenishment decision therefore needs to consider more than predicted sales. Current stock, goods in transit, distribution-centre availability, minimum-display requirements, order constraints, lead times, and service-level targets all affect how much capital should be committed to additional inventory.
As a retail demand forecasting and inventory optimization partner, Digitalplace.ai focuses on connecting these layers rather than treating the forecast as an isolated output. Demand can first be estimated at SKU and location level, then evaluated alongside store inventory, warehouse stock, goods in transit, minimum-display quantities, minimum-order requirements, supplier or transfer lead times, and other operating constraints. The system can then support replenishment quantities and allocation decisions across outlets, distribution centres, and supplier purchasing. From a working-capital perspective, the objective is not simply to reduce stock. It is to identify where inventory can be reduced safely, where availability needs protection, and where capital is currently tied up in stock that is unlikely to generate the expected return.
That is the point where forecasting becomes financial decision-making.
Allocation Can Release Working Capital Without Buying Less
One of the more interesting opportunities in inventory optimization is that improving working capital does not always begin with purchasing less.
Sometimes the first step is using the inventory the retailer already owns more effectively.
If Store A has excess stock while Store B is likely to run out, reallocating inventory may prevent Store B from placing an additional order. Similarly, better allocation from a distribution centre can reduce the need for stores to carry oversized buffers “just in case.”
This changes the question from:
“How much inventory should we remove?”
to:
“How much of our existing inventory is actually in the right place?”
Better allocation can improve the productivity of capital already deployed in the network.
What Should Retailers Measure?
Working-capital improvement should be measured together with inventory availability, not separately. Otherwise, financial gains may simply be the result of transferring cost from excess stock to lost sales.
Useful measures include:
- DSI;
- inventory turnover;
- total inventory value;
- excess or slow-moving stock;
- out-of-stock rate;
- lost sales;
- product availability;
- service level;
- markdown and waste;
- working capital released.
The relationship between these measures matters more than any one number.
For example, a reduction in inventory value accompanied by stable or higher availability is much more meaningful than inventory reduction alone. Likewise, lower DSI combined with rising stockouts may indicate that inventory has been cut too aggressively.
Working Capital Is the Outcome, Not the Starting Point
The strongest inventory strategies do not begin by asking, “How much stock can we cut?”
They begin by improving the decisions that create inventory in the first place: understanding demand more accurately, setting replenishment quantities more intelligently, and allocating stock to locations where it is most likely to sell.
Better operational decisions can then produce the financial result.
Lower excess inventory can reduce DSI. Better allocation can make existing stock more productive. More accurate replenishment can reduce both unnecessary buffers and avoidable stockouts. Together, those improvements can release working capital without treating customer availability as a secondary concern.
The best inventory optimization strategy therefore does not simply remove stock.
It removes the stock the business does not need while protecting the stock customers do.